Every commercial loan renewal, spread, tested and drafted for credit.
Inovagio is AI for commercial loan renewals: files gathered, spread with each figure traced to its page, and memos drafted against your policy. Your credit team decides.
We’ll spend 30 minutes with you on one of your workflows, and you don’t need to share any data.
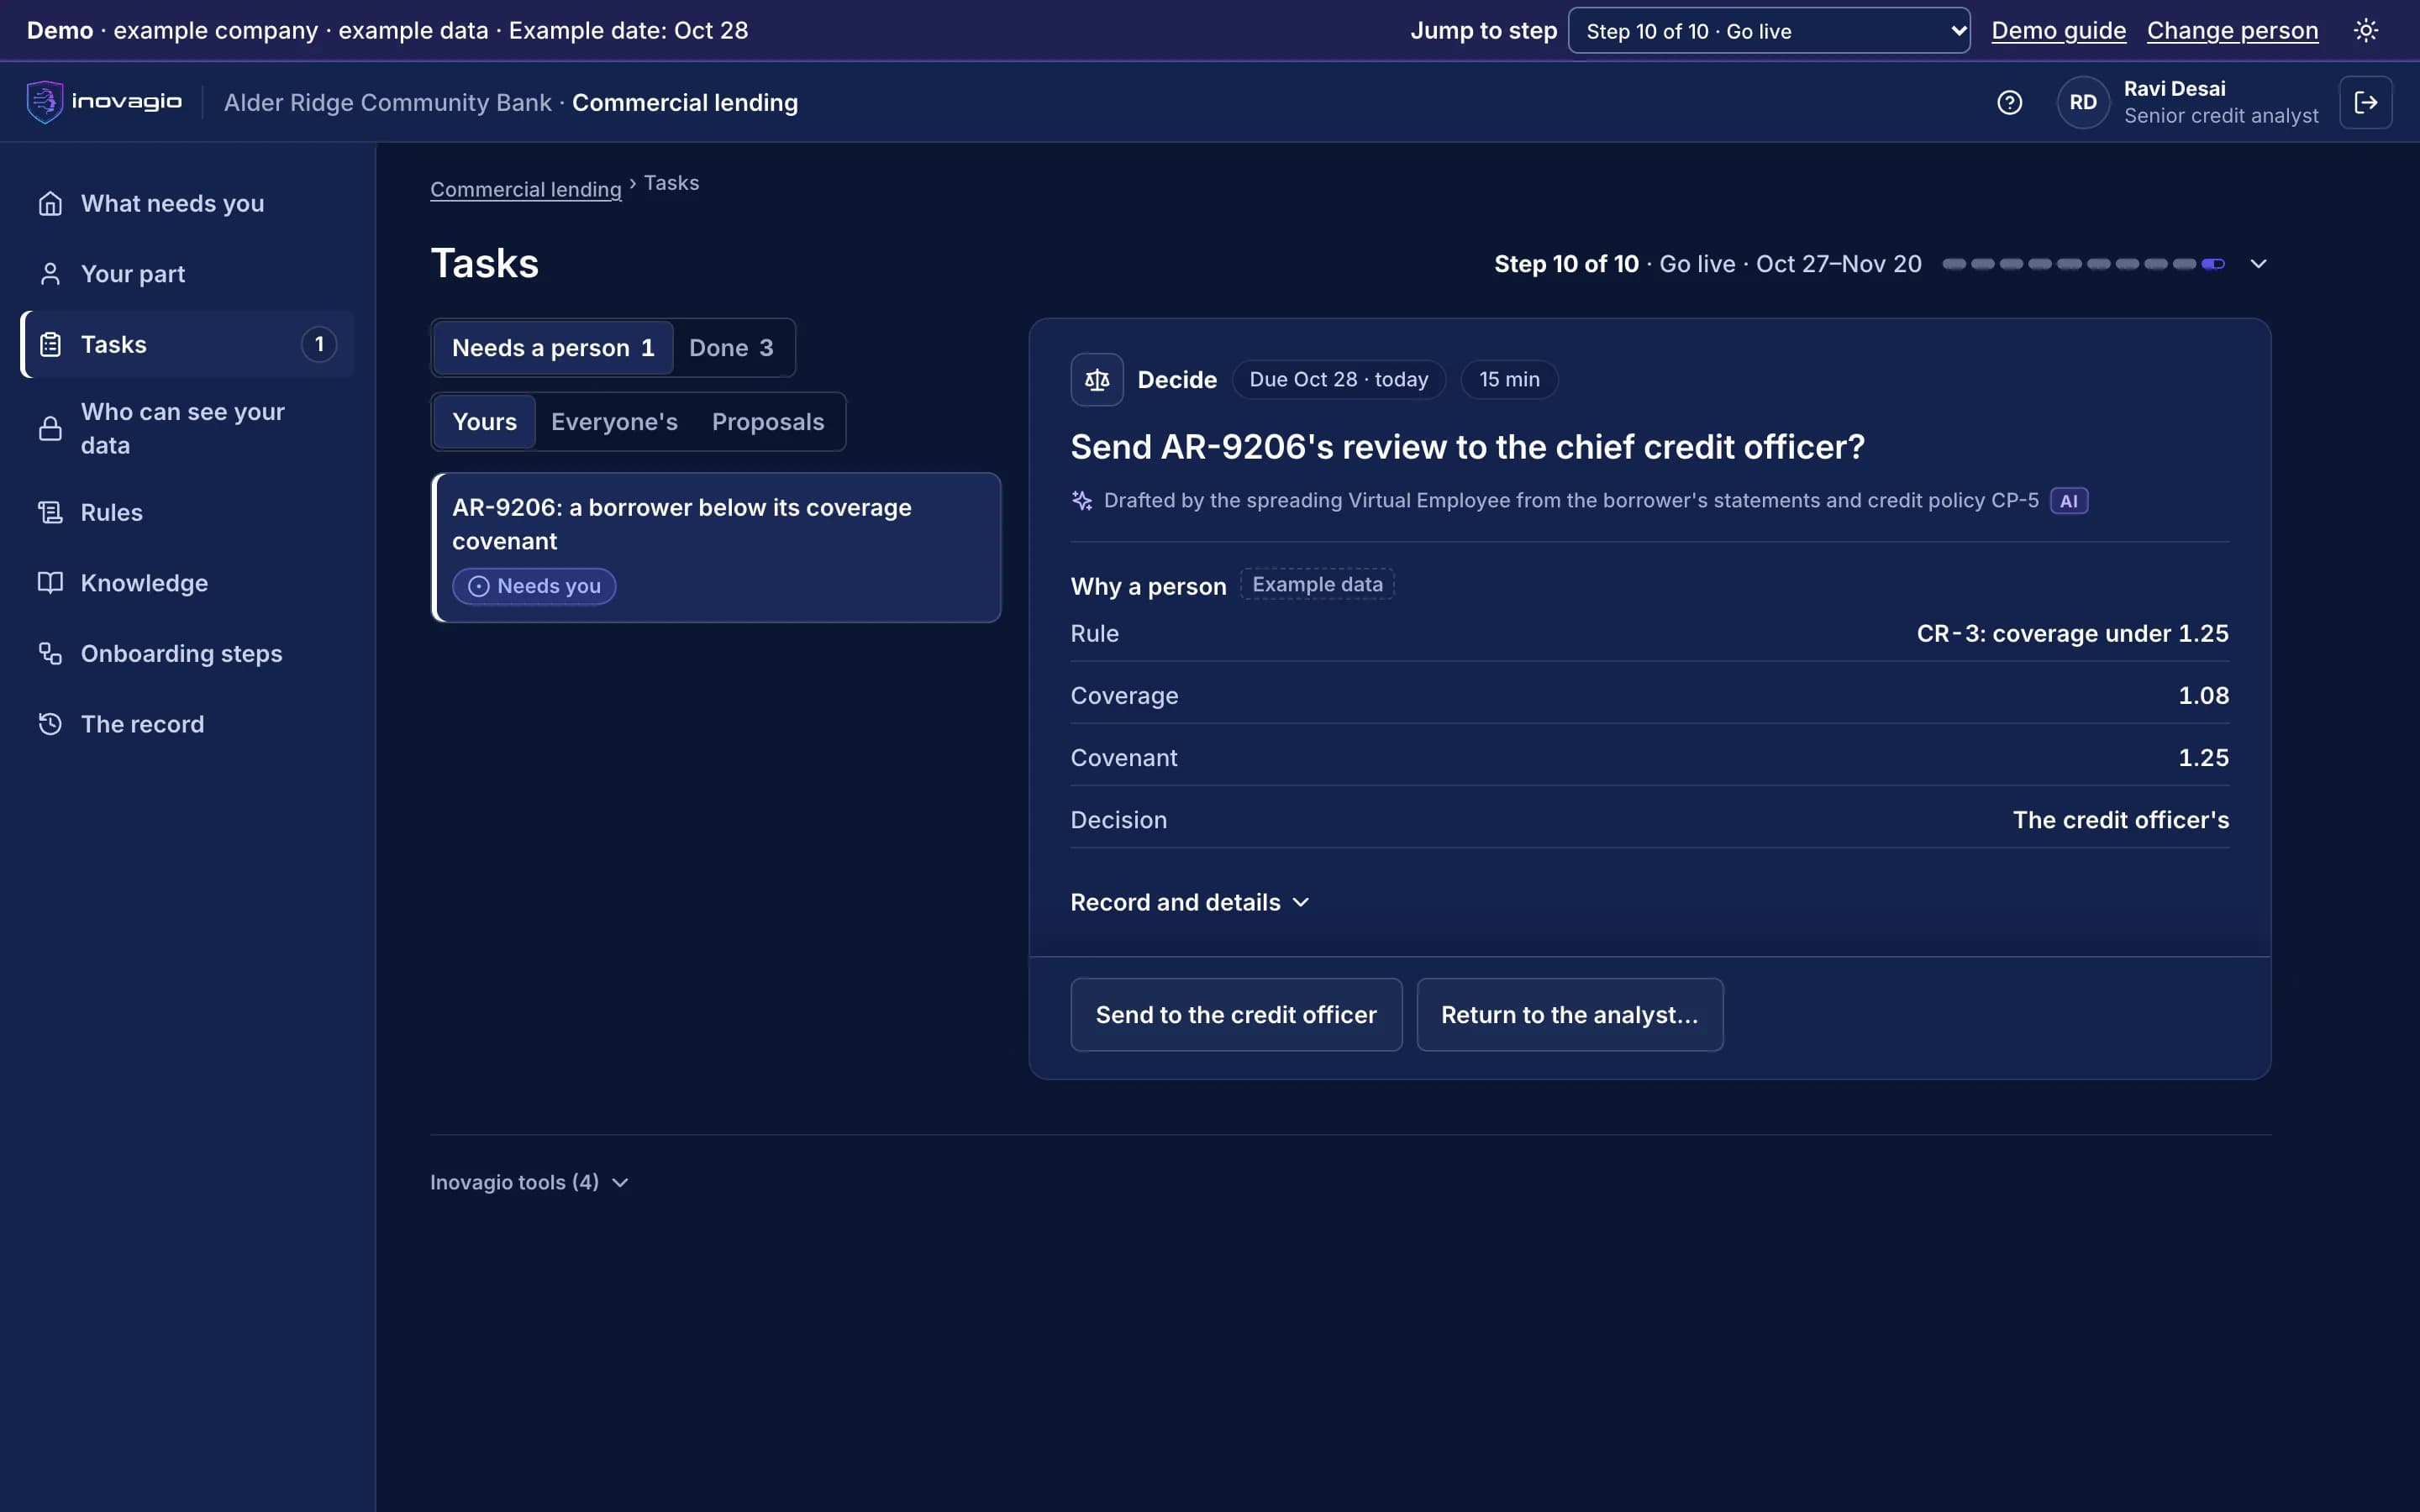
Pictured: an annual review at Alder Ridge Community Bank in the Inovagio App. The borrower is below its coverage covenant, so a senior credit analyst is asked to send the review to the chief credit officer (example company).
Credit union examiners will focus on lending in 2026.
2026
In its 2026 supervisory priorities, NCUA says examiners will focus on credit union lending, including portfolio monitoring and the management of any material credit risk concentrations.
From your first decision to live work: the ten steps at Alder Ridge Community Bank.
Alder Ridge Community Bank is an example company, not a customer. Its sponsor signs a charter for commercial renewals and annual reviews. Nothing touches live cases until the work has been tested, signed off, checked and run beside the team, and each kind of case goes live only when it clears the bar.
1 of 5 · Prepare · Steps 0–2
An account and a charter for annual reviews
0
Step 0: Open your account
Alder Ridge’s account opens in the bank’s own cloud account, and each Inovagio person is approved by name, steps and end date.
1
Step 1: Choose the work and sign the charter
The chief credit officer signs a charter for annual reviews: a target, a pass mark, a cost limit per file and when to stop.
2
Step 2: Set up sign-in and access
Analysts sign in with the bank’s accounts. The credit Virtual Employee starts with no access.
What your bank examiner sees: The signed charter, its stop rule, and who from Inovagio may enter the account, until when.
The borrower's statements, tax returns and certificates are collected, and missing ones are requested.
2 · Spread
The financials are spread by your spreading rules, each figure traced to its page.
3 · Test
Debt service coverage, loan to value and every covenant are tested against your policy.
4 · Draft
The review memo is drafted with the policy section behind each finding.
5 · Decide
Ravi checks the work. Renewals and exceptions go to the chief credit officer or the loan committee, as your policy sets.
Ravi’s day, senior commercial credit analyst at Alder Ridge Community Bank.
Alder Ridge Community Bank is an example company. “With Inovagio” is the target shadow mode measures, never a result.
Ravi’s day, senior commercial credit analyst at Alder Ridge Community Bank.
Part of the day
Today
With Inovagio
Collecting documents
Today: Chases each borrower by email for statements and returns
→
With Inovagio: Requests drafted and tracked; missing items listed
Spreading
Today: Keys figures from each return and statement
→
With Inovagio: Reviews spreads already done, each figure traced
Ratios and covenants
Today: Tests each covenant in a spreadsheet
→
With Inovagio: Sees each covenant's result against the policy limit
Review memo
Today: Writes each memo from the template and the spread
→
With Inovagio: Edits a drafted memo that cites the policy section
Exceptions
Today: Rebuilds the exceptions report by hand each quarter
→
With Inovagio: Every exception logged with its rule, approver and date
Exam preparation
Today: Pulls files and notes from shared drives
→
With Inovagio: Shows the record of each review and decision
What gets checked, and who decides.
Your credit policy, applied to every review
Coverage, loan to value and covenants are tested against the limits your policy sets, and each finding names the section.
Credit decisions stay with people
Credit decisions, covenant waivers, risk ratings and the reasons in adverse-action notices stay with your analysts, officers and committee.
Every exception logged for the board
Each policy exception records the rule, who approved it and when, so the board report draws from one log.
A record your examiners can follow
Each review keeps the documents used, the spread with its sources, the tests, the memo and the decision.
Credit decisions stay with your credit team.
Virtual Employees gather, spread, test and draft. A loan officer or the loan committee decides every renewal, exception and new loan (step 10).
Your data stays yours, end to end.
Alder Ridge's borrower files, statements and returns stay in its own cloud account, where it chooses to run, and never train anything for anyone else. No outside AI lab is needed to do this work.
Your credit policy, your files and your analysts don’t always agree.
In her interview, Helen says every commercial loan needs two years of tax returns. Ravi says: “For a renewal on the same terms, we take last year’s return and this year’s statements. Everybody knows that.” Two other analysts agree. Inovagio flags the gap instead of guessing. Helen proposes a rule, and the loan committee adopts it: renewals on unchanged terms need the latest return and this year’s statements; new money still needs two years of returns, with this year’s statements. That approved rule is now followed on every file.
Every gap between policy and practice goes to the person who decides it; nothing is guessed.
Every rule quotes the words it came from, by the speaker’s role, and names who approved it.
Nobody approves their own change, and every change is tested again before it runs.
Rule review · Commercial renewals · Alder Ridge Community Bank · example company
What the policy says
“Every commercial loan needs two years of tax returns.”Chief Credit Officer · interview
What the team does
“Renewals on the same terms go ahead with last year’s return and this year’s statements.”Three analysts · interviews
The rule its owner approved
“Same-terms renewals: latest return and this year’s statements. New money: two years of returns and this year’s statements.”Proposed by the Chief Credit Officer, adopted by the loan committee
In force on every file. The Virtual Employees follow version 2, and each finding links back to the rule and the interviews it came from.
Where Ravi’s team works, and how Inovagio connects.
We connect to each system the way it already supports, and reuse what exists before building anything new: read-only first, approved by the system’s owner, under its own limited identity (step 3). Your systems remain the system of record.
Core banking
Fiserv · Jack Henry · FIS · Corelation KeyStone
Vendor API · reads loans, payments and balances; writes nothing · limited worker identity
Loan origination
nCino · MeridianLink
Vendor API · reads applications and conditions; drafts memos for the analyst · limited worker identity
Mail connector · drafts document requests to borrowers for approval · limited worker identity
Each kind of data gets its protections before any work runs.
Each protection is a rule your privacy and security teams approve, proven with planted test values and checked again before go-live (steps 4, 7 and 8).
Borrowers’ personal and financial data
Fields the work doesn’t need are masked before indexing. Logs keep the category and the count, never the value.
Statements, returns and appraisals
Screened before a model reads them. An instruction found inside one carries no authority.
Cost per correct task: the AI and compute, the platform’s share, your people’s minutes at your rates, and any rework, divided by the work done correctly. Both sides are counted the same way, and every input comes from a record you can check.
Cost per annual review: today, and with Inovagio
What counts
Today
With Inovagio
Cost per annual review
Today: What each review costs you today, from your records and your team's estimates, by a method your finance lead approves. No one is timed.
With Inovagio: The same formula, counted the same way from shadow mode's own task records, at your rates
People's time
Today: Hours per review, from your team's estimates for each loan type
With Inovagio: Review and decision time, logged on every file
Reviews that need judgment
Today: Counted from last quarter's records
With Inovagio: Counted from the queue, every month
AI, compute and the platform
Today: Your current tools' share, if any
With Inovagio: Recorded on every task, with the platform fee's share
Rework
Today: Spreads or memos corrected after review
With Inovagio: A review corrected later counts against us
What shadow mode measures, and what it asks of your team.
What we measure
Hours per annual review
Reviews completed on time
Reviews that need judgment
Exceptions logged with an approver
Your team’s time
Each person sees what they will be asked, and roughly how long, against a weekly cap before the charter is signed. Nothing is approved because time ran out.
Who takes part
From your team: the credit administration lead, one credit analyst and the chief credit officer.
What IT does
IT provides read access to the core, the loan system and document imaging, and a mailbox for drafted requests.
A short form with the questions that matter. Scope, timing and terms are agreed on the workflow review.
Lending and account operations questions
What do state examiners check about AI?+
The CSBS supervisory framework for AI (September 2026) tells state examiners to check permissions, human checkpoints, logging, reversibility and the ability to shut automated work down. Each is a control here: a limited identity for every Virtual Employee, approval steps in your rules, a tamper-evident record, rule changes you can roll back, and a stop for one Virtual Employee, a department or everything at once. Our CSBS AI framework checklist maps each one to the record.
Does it make credit decisions?+
No. It gathers, spreads, tests and drafts. Your analysts check the work, and your officers and committee make every credit decision, waiver and risk rating.
How are the spreads checked?+
Every figure is traced to the page it came from, such as a line on the business tax return, so the analyst can check any number in one click.
Does it work with our loan origination system?+
It connects to loan origination systems such as nCino and MeridianLink, and to your core, under the permissions you set.
What about account opening?+
For a business's first account, it checks that each beneficial owner was identified and verified. For later accounts, it records the customer's confirmation that ownership is unchanged, where your procedure asks for one.
See how this works for your team.
A 30-minute briefing on one workflow of yours: whether it fits, what the first steps would be, and roughly what it would ask of your people. No data needed.